- CEO Brian Armstrong denies Coinbase caused the CLARITY Act’s Senate setback.
- Coinbase withdrew support in January, then backed the revised bill by May.
- The Senate vote failed 49-50 amid ethics and crypto policy disputes.
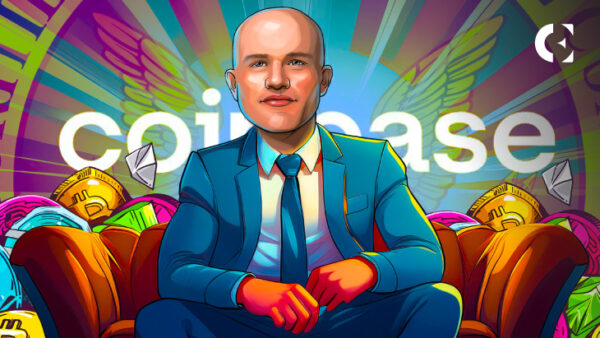
Coinbase CEO Brian Armstrong has denied that he or Coinbase are responsible for the CLARITY Act failing to move forward in the U.S. Senate. He said the bill failed because of changes to the legislation and unresolved political disagreements.
Armstrong spoke about the issue on Sept. 19 after saying The Wall Street Journal was preparing a story that would blame him and Coinbase for the bill’s failure.
Armstrong criticized the Journal, saying it had been against the CLARITY Act and was repeating arguments made by banking groups. He said Coinbase had supported federal crypto legislation for years, but temporarily opposed an earlier version of the bill because he believed some parts could hurt the crypto industry.
The dispute follows a Senate vote on Sept. 15. Senators voted 49-50 on whether to move forward with the CLARITY Act, but the bill needed 60 votes to pass the procedural step. The motion failed, although Republican Sen. Thom Tillis later introduced a motion to reconsider the vote.
Armstrong’s January Opposition
In January, Coinbase withdrew its support for the version of the CLARITY Act that was about to be reviewed by the Senate Banking Committee.
Armstrong said the bill needed changes related to DeFi, tokenized assets, the CFTC’s powers, and rewards for stablecoins. Coinbase was especially concerned about the rules on stablecoin rewards.
The disagreement was serious enough that the committee delayed its planned January review after Coinbase pulled its support. Much of the dispute focused on limits on stablecoin earnings, while Armstrong also raised concerns about tokenized stocks, DeFi, and how power would be divided between the SEC and CFTC.
He said the January version had serious problems that hurt the crypto industry. He also argued that the bill did not have enough support at the time and was unlikely to pass.
From Opposition to Support
The CLARITY Act was later revised. In May, Coinbase was supporting the bill again after senators reached a deal on stablecoin rewards. The deal banned rewards that worked like interest on bank deposits but allowed some rewards tied to actual use of crypto platforms and networks.
After the Senate Banking Committee approved the bill in May, Armstrong called the changes a “big improvement” for rewards, tokenization, DeFi and the CFTC’s authority. He also said he was glad Coinbase had raised its concerns earlier in the process.
By September, Armstrong said the final Senate version was “great” and that he “strongly supported it.”
Why Did the Senate Vote Fail?
The Sept. 15 vote failed for several reasons. One major issue was ethics rules involving President Donald Trump and his family’s crypto investments.
Several Democratic senators said the bill did not do enough to prevent possible conflicts of interest. According to reports, these concerns were a major reason Democrats opposed the bill.
Stablecoin rewards were another disagreement. Banking groups said crypto rewards will move money away from banks and reduce lending. Crypto companies argued that strict limits would hurt their products.
More importantly, Republicans did not have enough votes to reach the 60 votes needed to move the bill forward. Four Republicans voted against it, while Democrats and independent senators also opposed the motion.
In Sum
Essentially, the vote failed because of several unresolved issues, including ethics rules involving President Trump, stablecoin policies, and enforcement powers. Sen. Tillis’ motion to reconsider means the Sept. 15 vote did not necessarily end the process, although the bill remains uncertain as Congress moves toward the 2026 elections.
Related: CFTC Sends Crypto Rules to White House After CLARITY Act Setback
Disclaimer: The information presented in this article is for informational and educational purposes only. The article does not constitute financial advice or advice of any kind. Coin Edition is not responsible for any losses incurred as a result of the utilization of content, products, or services mentioned. Readers are advised to exercise caution before taking any action related to the company.