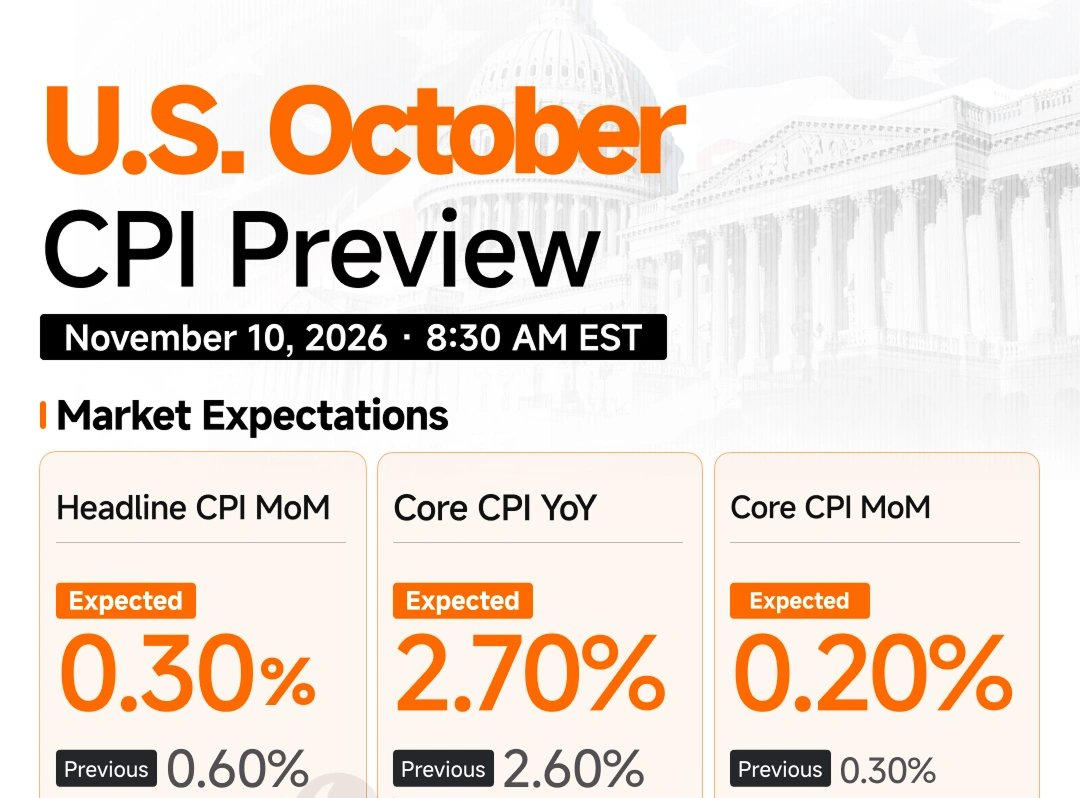
- US CPI is forecast at +0.3% MoM, with core CPI at +0.2%, down from September’s +0.6% and +0.3%, respectively.
- The US October CPI report is the final inflation reading before the Federal Reserve’s December meeting.
- The real concern for crypto traders now is whether the US inflation will actually decline or not.
The upcoming U.S. Consumer Price Index (CPI) report for October is set for release tomorrow, Nov. 10, 2026.
The report is highly anticipated as an important macroeconomic catalyst and the final publicly released CPI report before the Federal Reserve’s December meeting. Consensus forecasts headline CPI at +0.3% month-over-month (MoM) and core CPI to slow slightly to +0.2% MoM, down from September’s 0.6% and 0.3% readings, respectively.
Previous CPI Data vs. Tomorrow’s Forecasts
The US Bureau of Labor Statistics (BLS) will release the CPI report for October 2026 tomorrow. The consensus projections indicate that the monthly rate of inflation will cool in a noticeable way over September’s hot print. In the last September report, annual inflation stood at 3.7% following a 0.6% monthly rise, mainly fueled by a steep increase of 9.1% MoM in gasoline prices.
Meanwhile, market participants are closely eyeing a potential +0.3% MoM headline print, and consensus projections broadly expect headline CPI at +0.3% MoM and core CPI to slow slightly to +0.2% MoM. The expected slowdown is largely tied to softer energy effects, while core inflation is still seen as firm enough to keep December Fed tightening expectations in play.
Social Sentiment and Market Expectations
Discussion, including on X and in market commentary, is viewing tomorrow’s report as the last major CPI before the December Fed interest rate decision. Strong October jobs data, with payrolls up 165,000 versus much lower forecasts, with unemployment at 4.1%, have already pushed December hike odds toward about 80%, while the sentiment is cautious overall.
A softer-than-expected or in-line print, particularly on core CPI, is seen as possible modest relief that might slightly cut hike odds and provide some support to risk assets like equities and Bitcoin. An upward reading, especially when core is sticky, would solidify tightening expectations, boost yields and the dollar, and strain growth- and tech-sensitive assets.
Traders and analysts like @jeeniuzx and @Tom__Capital, emphasize on the details rather than the headline figure, and particularly core inflation, shelter costs, services, and any residual energy impacts, and the immediate response in 2-year and 10-year Treasury yields, the dollar, and stock indices.
Related: US CPI Report Today: What It Means for Bitcoin, Ethereum, XRP and Cardano Prices
Furthermore, in retail crypto and equity discussions, sentiment gauges like the CMC Crypto Fear and Greed Index are languishing deeply in “Fear” territory, currently at 28. Overall tone combines anticipation of monthly cooling with doubt that it will be enough to cause the Fed to meaningfully change course.
Will US Inflation Reduce or Not?
Consensus forecasts point to a clear slowdown from September’s unusually strong monthly CPI increase. A number of forecasts suggest a smaller monthly gain for both headline and core CPI, including the Bloomberg survey median close to 0.3%, the FactSet estimate of about 0.24%, the Cleveland Fed nowcast of 0.24%, and other analyst notes.
Related: US CPI and Core CPI DATA Will Drop Next Tuesday: Expect Major Volatility
That said, combined from those sources, the monthly rate of inflation is expected to be lower in October than the 0.6% headline and 0.3% core seen in September. That would mark a clear monthly cooling from September, although it would not necessarily mean annual inflation is falling sharply. But a core print around the consensus 0.2% would still suggest a high underlying rate annualized and above the Federal Reserve’s 2% target.
However, coupled with recent strong labor market data, the expected numbers are unlikely to eliminate the argument for policy caution or eliminate rate-hike expectations for December. Inflation is thus expected to be softer, while annual inflation remains elevated enough to keep the Fed cautious. But for markets and policymakers, the fine print of the report will be more important than the headline.
Disclaimer: The information presented in this article is for informational and educational purposes only. The article does not constitute financial advice or advice of any kind. Coin Edition is not responsible for any losses incurred as a result of the utilization of content, products, or services mentioned. Readers are advised to exercise caution before taking any action related to the company.